A Cebu condo is affordable for you if you can cover three things without strain: the cash before turnover (reservation and equity), the cash at turnover (other charges and move-in costs, plus any gap in your loan), and the monthly cost after turnover (loan payment, association dues and insurance). On our project pages, entry-level units start around ₱1.45M–₱1.6M for small studios outside the core cities and ₱2.4M–₱4M in Mactan, Cebu City and Mandaue. The trade-off: the lowest prices usually mean the smallest units, the farthest locations and the longest waits — and a low advertised monthly figure can hide a large payment later.
Key points
- The list price is only one number. In our worked examples, the cash needed before you can move in ranges from about ₱355,000 for a ₱1.6M studio to about ₱660,000 for a ₱4M studio.
- After turnover, the loan payment usually dwarfs the equity you paid during construction — budget for that step up.
- Ask every developer for a dated computation sheet that lists “other charges” in pesos, and whether VAT and parking are included.
- If you might struggle to keep paying, know your rights under the Maceda Law before you sign.
What entry level costs, area by area
These are the lowest starting prices on our Cebu project pages as of 3 October 2026. They show where the floor is in each area, not what is available today.
| Area | Lowest-listed unit on our pages | Listed from | Status |
|---|---|---|---|
| Liloan (outside the core cities) | La Bellezah Flats Liloan — studio, 18–23 sqm | ₱1.45M | Pre-selling |
| Consolacion (outside the core cities) | La Bellezah Flats Consolacion — studio, 18 sqm | ₱1.55M | Pre-selling |
| Talisay City | ATO Residences — studio, 18 sqm | ₱1.6M+ | Pre-selling |
| Cebu City — Pulangbato (upland) | La Bellezah Flats Pulangbato — studio, 18–23 sqm | ₱1.8M+ | Pre-selling |
| Lapu-Lapu City (Mactan) | Brentwood Mactan — studio, 20–24 sqm | ₱2.4M | Ready for occupancy |
| Cebu City — Guadalupe area | Guada Verde Towers (Kalunasan) — studio; Casa Mira Guadalupe — 20 sqm studio | ₱2,664,100+ / ₱2.8M | Pre-selling |
| Mandaue City | The Midpoint Residences — studio, 20 sqm | ₱2.9M | Pre-selling |
| Cordova | Balai Cordova — studio, 21 sqm | ₱3.7M+ | Pre-selling |
| Cebu City — Lahug | The Median Flats — studio, 22–26 sqm | ₱4M | Pre-selling |
| Cebu City — Mabolo | The Persimmon — studio, 23–32 sqm | ₱4M | Pre-selling |
| Cebu IT Park | Avida Towers Riala — studio, 22 sqm | ₱5M | See note |
| Cebu Business Park | Cerule at Solinea — studio, 24–25 sqm | ₱6.4M+ | Pre-selling |
Starting prices listed on our project pages as of 3 October 2026 — developer list prices with no quote date; developer price lists change, so ask for a current dated computation. Our pages do not state whether these prices include VAT, parking or other charges. Avida Towers Riala is recorded as pre-selling on our page but marketed by Avida as ready for occupancy. The cheapest 1-bedroom on our pages starts at ₱3.4M and the cheapest 2-bedroom at ₱5.5M, both at Primeworld District Mactan.
For the full unit-by-unit lists, see condos under ₱3M, under ₱5M and under ₱10M.
The costs that make up “affordable”
| Stage | What you pay | Who sets it |
|---|---|---|
| Reservation | A fixed fee to hold a unit — ₱5,000 to ₱100,000 on the entry-level pages we reviewed. Usually credited to the down payment and usually non-refundable. | Developer |
| Equity (down payment) | Typically 10%–20% of the price, spread over the construction period or paid in a lump sum. Some offers add a balloon payment at the end. | Developer |
| Other charges | Transfer taxes, registration and title costs, often billed as a separate line. VAT may apply depending on the price and the developer’s treatment. | Developer, BIR and LGU rules |
| Balance at turnover | The rest of the price, paid through a bank, Pag-IBIG or in-house financing. If the bank lends less than the balance, you cover the gap in cash. | Lender |
| Move-in costs | Advance association dues, utility deposits and connections, and any move-in or fit-out fees. | Building administration, utilities |
| Monthly after turnover | Loan amortization, association dues, mortgage redemption and fire insurance, and annual real property tax. | Lender, association, LGU |
Reservation range taken from our project pages for projects with units listed at ₱4M or less (lowest ₱5,000 at Guada Verde Towers; most ₱15,000–₱30,000; highest ₱100,000 at Plumera Mactan).
Four entry-level units, worked through
To show how the layers add up, we applied one set of assumptions to four units at different price points. The prices, sizes and equity terms come from our project pages; everything else is an assumption, and the developer’s own computation will differ.
Common assumptions: the balance is financed by a bank at 7% over 20 years; “other charges” equal 6% of the price; association dues are ₱80 per sqm per month; move-in costs are three months of dues in advance plus ₱15,000 for utility deposits and connections; the reservation fee is credited to equity. Insurance, real property tax and furnishing are not included.
| ATO Residences, 18 sqm studio | Brentwood Mactan, 20 sqm studio | Casa Mira Guadalupe, 20 sqm studio | Mandtra Residences, 20 sqm studio | |
|---|---|---|---|---|
| Listed price (our page) | ₱1,600,000 | ₱2,400,000 | ₱2,800,000 | ₱4,000,000 |
| Status | Pre-selling | Ready for occupancy | Pre-selling | Pre-selling |
| Equity terms (our page) | 15% over 36 months* | 10% over 24 months | 10% over 48 months | 10% over 48 months |
| Equity total | ₱240,000 | ₱240,000 | ₱280,000 | ₱400,000 |
| Average monthly equity | ₱6,667 | ₱10,000 | ₱5,833 | ₱8,333 |
| Other charges (6%, assumed) | ₱96,000 | ₱144,000 | ₱168,000 | ₱240,000 |
| Move-in costs (assumed) | ₱19,320 | ₱19,800 | ₱19,800 | ₱19,800 |
| Cash needed before moving in | ₱355,320 | ₱403,800 | ₱467,800 | ₱659,800 |
| Loan amount | ₱1,360,000 | ₱2,160,000 | ₱2,520,000 | ₱3,600,000 |
| Loan payment at 7%, 20 years | ₱10,544 | ₱16,746 | ₱19,538 | ₱27,911 |
| Association dues (₱80/sqm, assumed) | ₱1,440 | ₱1,600 | ₱1,600 | ₱1,600 |
| Monthly cost after turnover | ₱11,984 | ₱18,346 | ₱21,138 | ₱29,511 |
| Same, if the rate is 8% | ₱12,816 | ₱19,667 | ₱22,678 | ₱31,712 |
| Gross monthly income for a 30% housing share | ≈ ₱39,900 | ≈ ₱61,200 | ≈ ₱70,500 | ≈ ₱98,400 |
* Our ATO Residences page records ₱2,499 a month for 35 months and a balloon payment in month 36 for bank take-out with 15% down; the average shown spreads the same ₱240,000 evenly. Prices are as listed on our project pages on 3 October 2026; developer price lists change. The 30% figure is a planning guide, not a lender rule — each lender applies its own income test.
What the numbers show
- The step up at turnover is large. At Casa Mira Guadalupe, the average equity is about ₱5,833 a month; after turnover the modelled monthly cost is about ₱21,138 — more than three and a half times as much. Many buyers plan around the first number and are caught out by the second.
- The one-off charges are not small. In these examples, other charges and move-in costs add ₱115,000–₱260,000 on top of the equity. Get the developer’s actual figure in writing.
- A ready unit changes the timing, not the total. Brentwood Mactan’s shorter equity period means higher monthly payments now, but you can move in or rent sooner instead of waiting for construction.
- Price differences compound. The ₱4M Mandtra studio needs roughly 2.5 times the monthly income of the ₱1.6M ATO studio — for a unit only 2 sqm larger. You are paying for location and developer, so decide whether those matter to you.
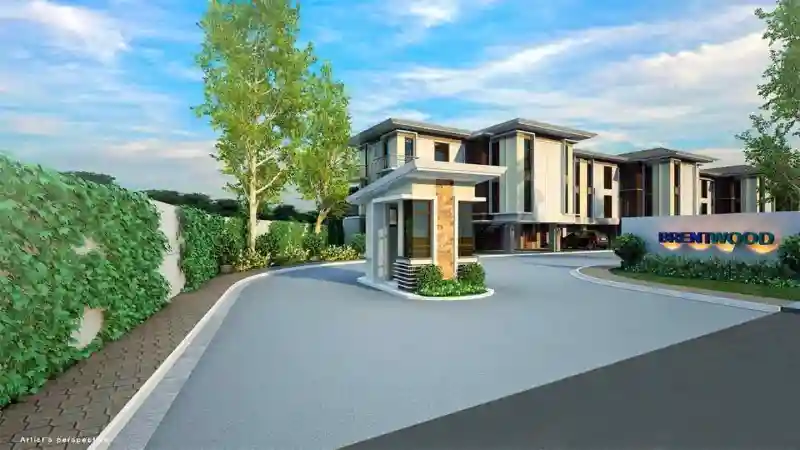
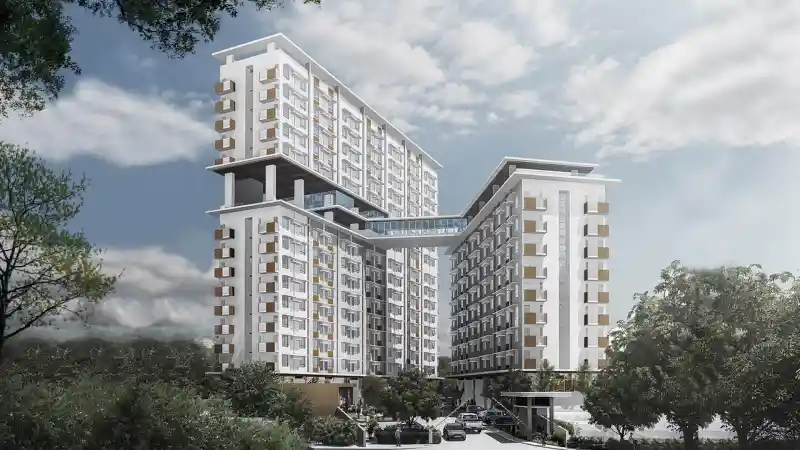
Projects used in the examples


How to work out your own number
- Start from the monthly cost after turnover, not the equity. Use our mortgage calculator with a rate a point or two above today’s, then add dues.
- Add up the cash you need before moving in: equity, any balloon, other charges and move-in costs. Our closing cost calculator estimates taxes and fees.
- Keep a buffer for an appraisal gap at turnover — the bank may lend less than your balance. Our bank financing guide explains why.
- Check the low-monthly offers. If a monthly figure looks very small, ask what happens at the end of the equity period and when the loan starts.
- Know your exit rights. Under the Maceda Law, installment buyers of residential units have grace periods and, after two years of payments, a right to a partial refund if the contract is cancelled.
Questions to put to the developer
- Is the reservation fee credited to the down payment, and is it refundable in any case?
- What exactly is in “other charges”, how much are they in pesos, and when are they due?
- Is the price VAT-inclusive? (Revenue Regulations No. 1-2024 sets ₱3.6M as the VAT-exemption ceiling for the sale of a house and lot or other residential dwelling — ask how it applies to your unit.)
- Is parking included, sold separately, or not available?
- What are the projected association dues per square metre, and what do they cover?
- Which banks and Pag-IBIG options does the developer accept for the balance, and what down payment does each require?
Frequently asked questions
What is the cheapest condo in Cebu right now?
On our project pages as of 3 October 2026, the lowest listed starting prices are studios of 18–23 sqm in Liloan (from ₱1.45M), Consolacion (from ₱1.55M) and Talisay City (from ₱1.6M), all pre-selling. Developer price lists change, so treat these as starting points and ask for a current dated computation. Our under-₱3M guide lists every unit type at that level.
Is the reservation fee extra, or part of the price?
It is usually credited toward your down payment, but not always, and it is often non-refundable if you back out. Check the reservation agreement for both points before you pay.
What happens if I can no longer pay the monthly equity?
For residential units bought on installment, the Maceda Law (Republic Act No. 6552) applies. If you have paid less than two years of installments, the seller must give a grace period of at least 60 days and can cancel only after a further 30 days’ notice by notarial act. After at least two years, you earn one month of grace per year paid, and on cancellation you are entitled to a refund of at least 50% of what you paid, rising after five years. Read your contract and get legal advice for your own case.
Can I use Pag-IBIG instead of a bank for an entry-level condo?
Often yes, if the project and unit qualify. Pag-IBIG requires at least 24 monthly savings and offers terms of up to 30 years, with age limits at application and maturity. Some developers set a different down payment for Pag-IBIG take-out — our ATO Residences page, for example, records 20% down with Pag-IBIG versus 15% with a bank. Confirm that the developer accepts Pag-IBIG for your unit before you reserve.
Find out what a specific unit will really cost you
Send us the unit you are considering and your monthly budget. We will request the developer’s current computation and lay out the cash you need before turnover, at turnover and every month after, with dates.
Request a cost breakdown WhatsApp +63 917 550 8229Sources and notes
- PropertEase project pages (listing data) — list prices, sizes, reservation fees and equity terms as recorded on our project pages, reviewed 3 October 2026; developer list prices with no quote dates
- Republic Act No. 6552 (Maceda Law) — Sections 3 and 4: grace periods, cash surrender value and cancellation for installment buyers of residential real estate, including condominium units
- Pag-IBIG Fund — Availment of a new housing loan — at least 24 monthly savings; up to 30 years; borrower not over 65 at application and 70 at maturity
- BIR — Revenue Regulations No. 1-2024 — VAT-exemption threshold of ₱3,600,000 for the sale of house and lot and other residential dwellings, effective 1 January 2024
- Cebu Landmasters — Casa Mira Towers Guadalupe — developer and address
- Cebu Landmasters — Mandtra Residences — developer and address
- PrimaryHomes — Brentwood — developer and location; ready for occupancy
- Worked examples — equity percentages and terms are as recorded on our project pages; the 7% and 8% loan rates, 20-year term, “other charges” at 6% of price, association dues of ₱80 per sqm per month, ₱15,000 of utility deposits and the 30%-of-income guide are assumptions for illustration, not quotes from any developer, association or lender; loan payments use the standard amortization formula